Loan Application Process: What Happens After You Submit?
After you submit a loan application, your information moves into review. The lender checks it for completeness, may verify your identity and income, and then decides whether to approve, deny, request more details, or present terms. Funding follows only after you review and sign the agreement.
CreditCube loans are issued by a tribal lending entity subject to tribal and federal law, not state law. When you apply, automated underwriting does the first review. It checks your identity and income details and estimates whether the payments would fit your budget. Some applications go to a team member for manual review or need more documents. All decisions are made at the lender's discretion, and approval is not guaranteed.
This guide explains the post application process, the loan review timeline, possible statuses, and what to check before you accept a loan. Want to know if you may qualify? Check your eligibility on our loans for bad credit page, where you can also see how these loans work and what they cost. Checking does not guarantee approval, a loan amount, funding timing, or specific terms.
Disclaimer: This is educational content only. It is not financial, credit, tax, or legal advice. CreditCube does not guarantee the accuracy, completeness, or suitability of this information for your circumstances. CreditCube is not responsible for any financial loss, debt, or adverse outcome resulting from actions taken based on this content.
What Happens After You Submit a Loan Application?
The loan application process continues after you click submit. Your submission starts the review stage.
First, CreditCube receives your application and checks it for completeness. CreditCube may then verify your identity and eligibility. It may also review your income and repayment ability. After that, CreditCube may approve or deny the application, ask for more information, or present terms. If CreditCube approves your application, you review and sign the agreement. CreditCube sends funds only after you complete each required step.
The review moves through clear stages. Here is how each one works.
Loan Application Process Step by Step
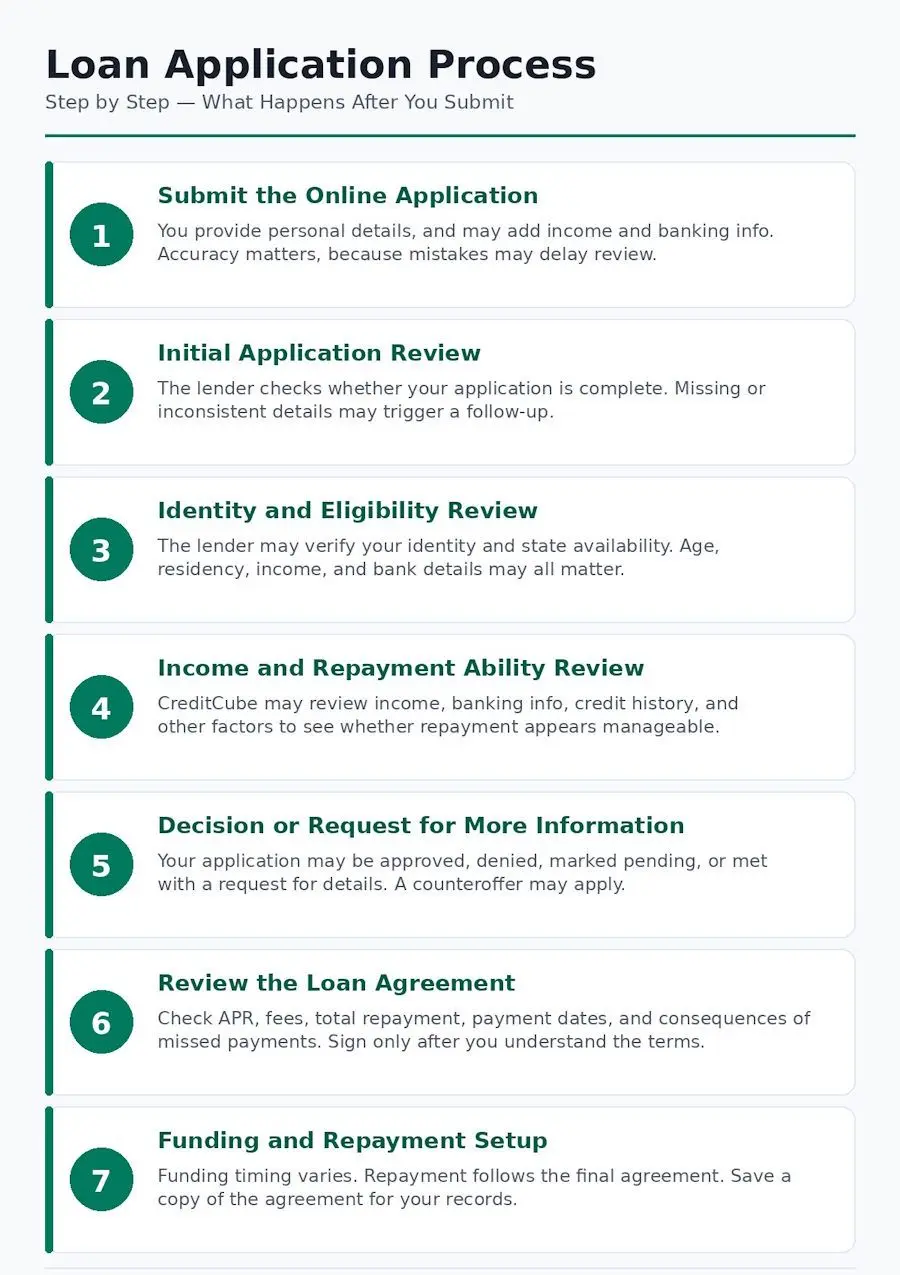
- Submit the Online Application. CreditCube keeps the first step simple: provide your personal details to get started. You may also share income and banking details. Check your entries before you submit, because mistakes may delay review.
- Initial Application Review. CreditCube checks whether your application is complete. If details are missing or don't match, CreditCube may contact you to follow up.
- Identity and Eligibility Review. CreditCube may verify your identity and confirm that loans are offered where you live. It may also look at your age, residency, income, and bank account details.
- Income and Repayment Ability Review. CreditCube may review your income, banking information, credit history, and other eligibility factors. This helps CreditCube understand whether repayment appears manageable. This review does not guarantee approval. CreditCube may request additional information or decline applications at its discretion.
- Decision or Request for More Information. CreditCube may approve or deny your application, mark it pending for manual review, or ask for more details. In some cases, CreditCube may make a counteroffer. CreditCube does not guarantee that counteroffers will be available. Counteroffer availability depends on eligibility and lender discretion.
- Review the Loan Agreement. CreditCube lists the APR, fees, total repayment amount, payment dates, and the consequences of missed payments in your agreement. Check each one, and sign only after you understand the terms.
- Funding and Repayment Setup. CreditCube sends funds after you sign, and funding timing varies. Your repayment schedule follows the final agreement. Save a copy of the agreement for your records.
Timing matters at each stage. Here is a look at how long things can take.
Loan Review Timeline: How Long Can It Take?
| Stage | What happens | What can affect timing |
|---|---|---|
| Application submission | Borrower sends information | Incomplete or incorrect details |
| Initial review | Lender checks application | Volume, business hours, missing data |
| Verification | Identity, income, and bank details may be checked | Document quality or mismatched information |
| Decision | Application may be approved, denied, pending, or need more info | Manual review or eligibility concerns |
| Agreement signing | Borrower reviews and signs terms | Borrower response time |
| Funding | Funds are sent if approved and signed | Bank processing and timing |
Timing can vary. These estimates are general only. Actual timing depends on the lender, application complexity, verification needs, and bank processing. CreditCube does not guarantee specific timelines. To see how this works in specific cities, read about installment loans in Plano, TX and installment loans in Corpus Christi, TX.
One status often raises questions, so let's look at it next.
What Does "Pending" Mean After a Loan Application?
A pending status may mean a few things. The application is still being reviewed. More information is needed. Documents need to be verified. The lender is checking eligibility, or a manual review is required.
Pending does not automatically mean approved or denied. It simply means a decision has not been reached yet.
Sometimes an application needs a closer look. Here is why that can happen.
Why Your Loan Application May Need More Review?
- Missing information. Blank fields can pause the review until they are complete.
- Typo in personal details. A small error can create a mismatch that needs checking.
- Income verification needed. The lender may confirm your income before deciding.
- Bank account verification needed. Account details may need to be checked.
- Identity verification issue. A mismatch can trigger an extra step.
- State availability review. The lender may confirm loans are offered in your state.
- Inconsistent application details. Conflicting entries may need clarification.
- Manual review. Some applications are reviewed by a person rather than a system.
The best way to reduce delays is simple. Respond to lender requests with accurate information and read messages carefully.
Different lenders review different things. Here is what the process looks like at CreditCube.
What CreditCube Reviews After You Apply
CreditCube may look at several details after you apply. These include:
- Personal information
- Eligibility information
- Income or repayment ability
- Bank account information
- State availability
- Final loan terms
- Required disclosures and agreement
At CreditCube, the review is intended to help determine whether an applicant may qualify for a tribal installment loan and what terms may apply. Approval is not guaranteed, and final terms are provided before signing.
Here is how those steps flow in order.
CreditCube's Post Application Process
- Application received. CreditCube receives your submitted application.
- Information reviewed. Details are checked for completeness and eligibility.
- Additional information may be requested. Respond accurately and promptly if asked.
- Decision or next step. If eligible, you may be shown loan terms.
- Agreement review. You review the repayment schedule, cost, and obligations.
- Funding process. If approved and signed, funding timing depends on processing factors.
Before you sign anything, take a moment to review the details. Here is a checklist.
What to Check Before Signing a Loan Agreement
- Loan amount. Confirm the sum matches what you asked for and expect to receive. A figure that looks off could signal an error or a fee rolled into the total.
- APR. This is the yearly cost of borrowing, including interest and certain fees. It gives you a clearer picture than the interest rate alone.
- Fees. Note any charges tied to the loan, such as origination or processing fees. Knowing these upfront helps you see the real cost.
- Total repayment amount. This is what you will pay in full by the end of the loan. Comparing it to the amount borrowed shows the true price of the loan.
- Payment schedule. Check how often payments are due, whether weekly, biweekly, or monthly. Make sure the rhythm lines up with when you get paid.
- Due dates. Confirm the exact dates each payment is owed. Missing one can lead to fees or added costs.
- Early repayment terms. Review whether you can pay the loan off ahead of schedule. Some agreements allow it freely, while others may add conditions.
- Late or missed payment consequences. Understand what happens if you fall behind, including any fees or reported effects. Knowing this helps you plan and avoid surprises.
- State availability. Confirm the loan is offered where you live. Terms and rules can differ from one state to another.
- Contact information. Keep the lender's phone, email, or support details handy. You may need them for questions or payment issues later.
- Whether repayment fits your budget. Make sure the payments work alongside your other expenses. A loan should ease a situation, not strain it.
A loan agreement should not be signed until you understand the cost, repayment schedule, and possible consequences of missed payments.
Not every application is approved. Here is what a denial means.
What Happens If Your Loan Application Is Denied?
Denial can happen for many reasons. Depending on the lender and applicable law, you may receive a notice or an explanation. If so, review the reason and correct any errors that apply. CreditCube may provide adverse action notices as required by applicable law. However, other tribal lenders may have different notice requirements. Review all communications carefully. Avoid taking on unaffordable debt elsewhere right away. A denied application does not mean every future application will be denied. It means the lender could not approve the application based on the information reviewed at that time.
You can also take simple steps to keep things moving. Here are a few.
How You Can Avoid Delays in the Loan Application Process?
A few simple habits can keep your application moving and reduce the chance of a hold-up. Try these steps.
- Enter accurate personal information. Correct details prevent mismatches during verification. Even a small error can pause the review while it gets sorted out.
- Use your legal name. Match the name on your official ID and bank records. This helps the lender confirm your identity without extra steps.
- Double-check income details. Accurate figures support a smoother review. Numbers that do not line up may trigger a request for proof.
- Make sure bank information is correct. Errors here can slow funding or stop it entirely. Confirm your account and routing numbers before you submit.
- Watch for emails, calls, or texts. The lender may reach out with questions or requests. A quick reply keeps your application on track.
- Submit requested information clearly. Clear, complete responses reduce back-and-forth. Send exactly what is asked for, and nothing missing.
- Review terms before signing. Read the agreement so you know what you agree to. Understanding the terms now prevents surprises later.
- Apply during business hours if timing matters. Applications sent while staff are working may be seen sooner. This may help, though results are not guaranteed.
Beyond the process itself, it helps to think about the bigger picture. When does a loan actually make sense?
When a Loan May Make Sense and When to Reconsider
A loan may be worth considering in some situations. The expense is necessary. The need is temporary. Repayment fits your budget. You understand the total cost. And you have reviewed other options first.
A loan may not be the right choice in others. You cannot afford the repayment. You are using debt for ongoing expenses. You would need another loan to repay this one. The cost is unclear. Or you have not reviewed the full agreement.
This section provides general information only. It does not constitute financial advice or a recommendation regarding your specific situation. CreditCube does not assess your individual circumstances or recommend whether a loan is appropriate for you.
Before you apply, it is worth weighing other paths. Here are a few to explore. You may also find short term personal loans useful for comparison.
What Alternatives Can You Consider Before Applying?
- Payment plans with service providers. Many providers let you split a large bill over several months. Ask your utility, medical, or phone company whether they offer one before you borrow.
- Employer paycheck advances. Some workplaces let you access earned pay ahead of payday. This can cover an urgent cost without interest or fees.
- Emergency savings. Money you have set aside is the cheapest option available. Even a small fund can absorb a surprise expense without new debt.
- Budget adjustments. Trimming a few expenses for a short time may free up cash. Review subscriptions, dining, and other flexible costs first.
- Negotiating bill due dates. Many companies will shift a due date if you ask. Lining up bills with your payday can ease a tight month.
- Nonprofit credit counseling. Free or low-cost guidance is available from trusted nonprofit groups. A counselor can help you build a plan before you take on more debt.
- Asking whether the expense can be delayed. Some costs are not as urgent as they first seem. Waiting a short while may remove the need to borrow at all.
For broader guidance on responsible borrowing, the Consumer Financial Protection Bureau offers free educational resources.
What Happens After You Submit a Loan Application?
After you submit a loan application, the lender reviews your information, checks eligibility, verifies details, and decides whether to approve, deny, request more information, or provide terms. If approved, review the loan agreement carefully before signing. The loan review timeline depends on the lender, application accuracy, verification needs, business hours, and bank processing.
FAQs - Loan Application Process
What happens after I submit a loan application?
After you submit a loan application, the lender reviews your information, checks eligibility, verifies details, and decides whether to approve, deny, request more information, or provide loan terms.
How long does the loan review timeline take?
The loan review timeline varies by lender, application details, verification needs, business hours, and bank processing. Some reviews may be faster, while others require additional information.
What does pending mean in the post application process?
Pending usually means the application is still being reviewed or the lender needs more information before deciding. It does not mean the application is approved or denied.
Can I be denied after submitting a loan application?
Yes. A lender may deny an application based on eligibility, repayment ability, state availability, verification results, or other application details.
What should I do if the lender asks for more information?
Respond with accurate information and review the request carefully. Missing, unclear, or incorrect details may delay the application process.
Does submitting a loan application guarantee approval?
No. Submitting a loan application does not guarantee approval, loan amount, terms, or funding. Final decisions depend on lender review and eligibility.
When do funds arrive after approval?
Funding timing depends on approval, agreement signing, lender processing, bank processing, and when the application is completed. Confirm exact timing in the final loan agreement or lender communication.
Recent Articles
Best OneMain Financial Alternatives for Personal Loans
Personal loans available online or in-branch with secured and unsecured opti...Installment Loans vs Payday Loans: Which Is Safer and Smarter in 2026
Compare installment loans vs payday loans in 2026 explore risks, benefits, r...Bad Credit Dental Financing: Options & Costs Guide
Bad credit dental financing explained. Learn options, costs, and safe ways t...$500 Payday Loans Online Same Day - Fast Cash Guide
$500 payday loans online same day explained. Learn how they work, requiremen...Personal Holiday Loans: What Borrowers Should Know
Personal holiday loans explained. Learn how they work, eligibility requireme...BSA AML Compliance: How Lenders Keep Loans Safe
BSA AML compliance helps lenders monitor risk and protect borrowers. Learn h...Get your money today
Apply for a loan NOW!
Applying does NOT affect your FICO® Score!
Have questions?
Please call us by phone:
Credit Cube © 2026. All rights reserved
CreditCube is a Tribal enterprise, wholly owned and operated by the Big Valley Band of Pomo Indians, a federally-recognized American Indian tribe and sovereign government. Any Agreement entered into as a result of this Application shall be governed by applicable Tribal and federal law. Each aspect of communication and transaction with/on this site will be deemed to have occurred in CreditCube’s Big Valley Band of Pomo Indian Reservation offices, regardless of the location where you are accessing or viewing this site.
⚠ Please note: This is an expensive form of borrowing. CreditCube loans are designed to assist you in meeting your short-term borrowing needs and are not intended to be a long-term financial solution! Examples of emergency reasons why these loans might be used include unexpected emergencies, car repair bills, medical care, or essential travel expenses.
* Loan approvals are subject to underwriting. Approval may take longer if additional verification documents are requested. Not all loan requests are approved. CreditCube reviews your information in real-time to determine whether your information meets our lending criteria. You acknowledge that by completing and submitting the website application that you are applying for a Loan. We verify applicant information through national databases including, but not limited to, Clarity Services, Inc., a credit reporting agency, and we may pull your credit in order to determine your eligibility and ability to repay.
** Maximum loan amount is $500 for first-time customers. For returning CreditCube customers, rates may go down over time based on your CreditCube Loyalty Program status and your payment history with us. Please see our Loyalty Program page for more information.
*** Loan Applications processed and approved before 3pm EST Monday-Friday are typically funded on the next business day. Example: If your loan is processed and approved on Friday before 3pm EST, the loan will typically be funded on the following Monday. Deposit times may vary depending on your bank. Business Day means Monday through Friday excluding all federal banking holidays.
CreditCube does not lend to residents of Pennsylvania, Connecticut, Minnesota, New York, Vermont, Virginia, West Virginia, Illinois, Georgia and North Carolina. Availability of installment loans in your state is subject to change at any time with or without notice at the sole discretion of CreditCube.