What is the Truth in Lending Act (TILA) and Why it Matters?
The Truth in Lending Act (TILA) requires creditors to give you clear information about the cost and terms of consumer credit. These disclosures can include the APR, finance charges, payment schedule, total of payments, and other key loan terms. TILA loan regulations help you compare credit offers and understand your repayment obligations before you sign. TILA is tied to Regulation Z, the rule that puts it into practice. It does not set interest rates or guarantee approval; its job is transparency.
This article is general educational information, not legal advice. For your specific situation, consider speaking with a qualified professional.
What Are TILA Loan Regulations?
TILA loan regulations are the disclosure rules that require lenders to spell out certain credit costs and terms before you agree to a loan. They apply to many consumer credit products, each a little differently.
These rules reach installment loans, credit cards, auto loans, mortgages, and other consumer credit. From a soft credit check loans option to a mortgage, the goal is the same: clear terms you can review. The rules focus on disclosure, not on promising that a loan is affordable or right for you.
Why Does the Truth in Lending Act Matters to Borrowers?
The Truth in Lending Act matters because it helps you understand the full cost of borrowing, not just the monthly payment. With standard disclosures, you can compare offers side by side and see your repayment obligations clearly.
It is easy to focus only on the payment amount. TILA helps show the bigger picture: the interest, the fees, the APR, and the total you will repay. The CFPB notes that TILA requires lenders to disclose the APR, so you can compare one offer against another. That transparency encourages a careful review before you sign.
Key TILA Disclosures Borrowers Should Review
The key TILA disclosures to review are the APR, the finance charge, the amount financed, the total of payments, the payment schedule, and the late-payment terms. The table explains what each one means.
The following summarizes disclosures generally applicable to covered closed-end installment loans. Credit cards and mortgages have different disclosure requirements and formats.
| Disclosure | What it means | Why it matters |
|---|---|---|
| APR | The annual cost of credit, as a percentage | Helps you compare credit offers |
| Finance charge | The dollar cost of credit | Shows how much borrowing may cost |
| Amount financed | The amount of credit provided to you or on your behalf, calculated under Regulation Z after subtracting prepaid finance charges. It may differ from the principal balance or cash deposited into your account. | Separates principal from charges |
| Total of payments | The total paid after all scheduled payments | Shows the bigger repayment picture |
| Payment schedule | The number, amount, and timing of payments | Helps you plan repayment |
| Late payment terms | The possible consequences of missed payments | Helps you understand the risk |
These figures turn a loan from a guess into something you can measure.
What TILA Does Not Do
TILA does not guarantee approval, set a loan's cost, or replace reading the full agreement. It supports transparency, but it does not decide whether borrowing is right for you.
- It does not guarantee approval. No lender must approve every applicant.
- It does not set the price. A loan can still be expensive.
- It does not replace the agreement. You still need to read every term.
- It does not remove repayment duties. You still owe what you borrow.
- It does not override state rules. State and product-specific requirements still apply. Other applicable laws may provide additional protections. TILA generally preserves state laws except to the extent they are inconsistent with federal requirements; specific preemption rules apply.
So the disclosures are a starting point, not the whole decision. You should still review the full agreement and whether repayment fits your budget.
This section is general information, not legal advice or a lending decision. Whether a loan suits you depends on your own circumstances.
Truth in Lending Act vs. Regulation Z
The difference is simple: the Truth in Lending Act is the federal law, and Regulation Z is the rule that puts it into practice. Many sources use the two names together.
| Term | Simple explanation |
|---|---|
| Truth in Lending Act | The federal consumer credit law |
| TILA | The common abbreviation for the Truth in Lending Act |
| Regulation Z | The regulation that implements TILA |
| TILA disclosures | The loan cost and term information you receive |
You do not need to know every legal section. You just need to understand the disclosures you receive. For a deeper look, see the CFPB's overview of the Truth in Lending Act. Next, here is how all of this applies to an installment loan.
TILA and Installment Loans: What Applies
For installment loans, TILA disclosures help you review the cost of credit, the payment timing, and your repayment obligations before you sign. An installment loan is repaid in scheduled payments, so the schedule and total cost matter most.
This is where a lender like CreditCube fits in. CreditCube offers tribal installment loans for eligible borrowers, whether for a planned expense or a home improvement loans need. Whatever the purpose, you should review all terms carefully before accepting any agreement. These loans can be expensive, so the disclosures are worth a close read.
Checklist: Using TILA Disclosures Before You Sign
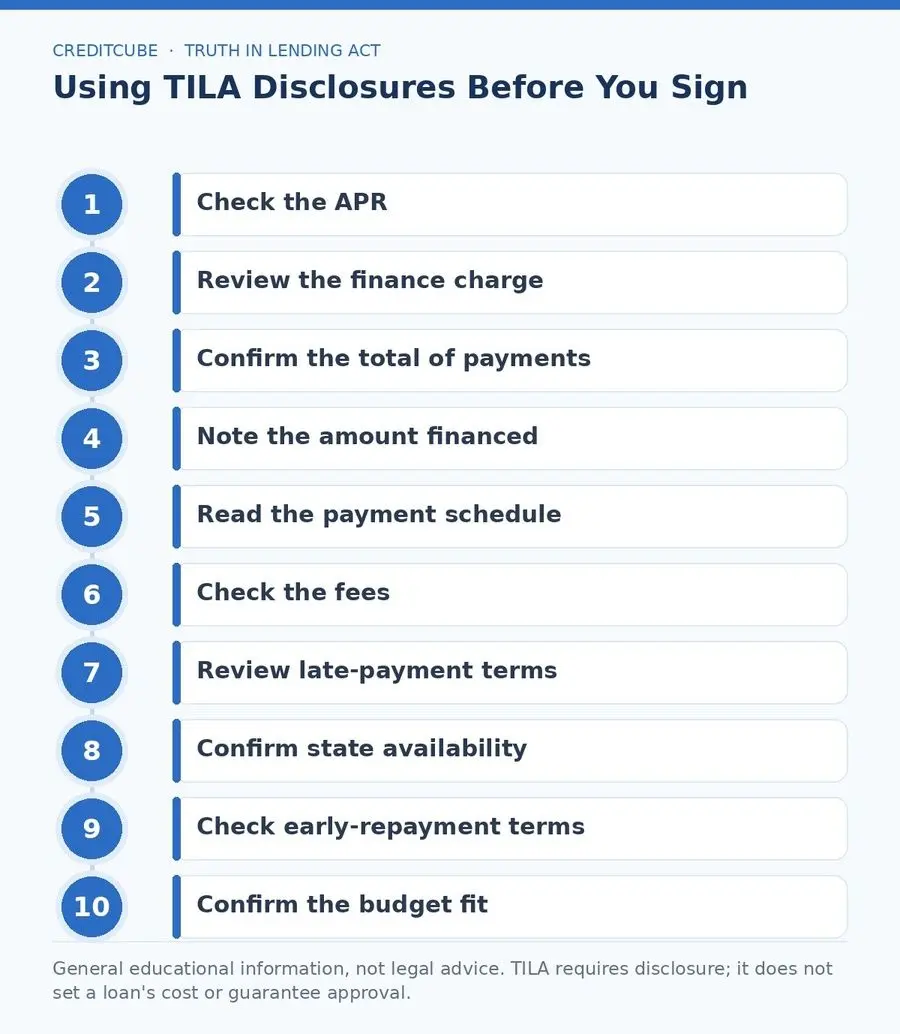
Before you sign, use the disclosures to review the APR, the finance charge, the total of payments, the payment schedule, and the fees. Run through each point below.
- APR. The yearly cost of the credit.
- Finance charge. The dollar cost of borrowing.
- Total of payments. The full amount you will repay.
- Amount financed. The loan amount you receive.
- Payment schedule. When and how much each payment is.
- Fees. Any charges beyond interest.
- Late payment terms. What happens if you miss a payment.
- State availability. Whether the loan is offered where you live.
- Early repayment terms. Check the required disclosure about any prepayment charge or entitlement to a rebate of finance charges, as applicable.
- Budget fit. Whether the payment works with your budget.
If the payment schedule does not fit your budget, consider alternatives before borrowing. It also helps to know the traps that catch many borrowers.
Common Mistakes When Reading Loan Disclosures
The most common mistake is looking only at the monthly payment and ignoring the total cost. A few others trip up borrowers too.
- Watching only the payment. A low payment can hide a high total cost.
- Ignoring the total repayment. This is what the loan really costs.
- Confusing interest rate with APR. The APR includes certain fees; the rate does not.
- Skipping the due dates. A missed date can mean a late fee.
- Overlooking late-payment terms. Know the cost of a missed payment first.
- Assuming approval means affordable. Approval does not mean the loan fits your budget.
- Skipping the full agreement. The agreement is what binds you.
Avoiding these keeps the disclosures working in your favor. Here is how a lender fits into that review.
CreditCube and Clear Loan Review
CreditCube provides tribal loans repaid in installments. It is not a guaranteed solution. Before signing, you should review your agreement, repayment schedule, costs, and all required disclosures. This is expensive form of borrowing with APRs ranging from 200% to 700%.
Reading those disclosures helps you understand the cost and plan repayment. CreditCube is not a fit for every borrower, and approval depends on eligibility. Read the full agreement together with the required disclosures. Agreement terms remain subject to applicable law and do not override statutory consumer protections.
This section is general information about loan review, not financial advice or a statement about any specific account. Your own loan agreement governs your loan.
Alternatives to Borrowing
A loan is not the only option. Before you borrow, consider whether the expense can be delayed, reduced, or covered by a lower-cost alternative.
- Provider payment plans. Ask a service provider to spread a bill over time.
- Budget adjustments. Trim other spending to free up funds.
- Emergency savings. Use savings to avoid new debt.
- Employer paycheck advance. Some employers advance part of your next check.
- Nonprofit credit counseling. A counselor can help you build a plan for little or no cost.
- Waiting or reducing the expense. Delay or scale it back when you can.
If none of these fit and you do decide to borrow, one last check helps.
How to Borrow Responsibly?
Before you sign, confirm you understand the APR, the finance charge, and the total repayment, and that you can pay without missing essentials. Answer yes to each of these.
- I understand the APR.
- I understand the finance charge.
- I know the total repayment amount.
- I know when payments are due.
- I can make payments without missing essential expenses.
- I have reviewed alternatives.
- I have read the full agreement before signing.
Conclusion
The Truth in Lending Act helps you understand the real cost of credit before you commit. Its disclosures — the APR, finance charge, total of payments, and more — let you compare offers and see your repayment obligations. Use them to make a clear-eyed choice. If you borrow from CreditCube, review all loan terms before signing, and weigh borrowing carefully against your alternatives.
FAQs About the Truth in Lending Act
What is the Truth in Lending Act?
It is a federal consumer protection law that requires creditors to give you clear information about the cost and terms of certain consumer credit products.
What does TILA stand for?
TILA stands for the Truth in Lending Act.
What are TILA loan regulations?
TILA and Regulation Z require credit-cost disclosures and provide additional protections that vary by product, including certain billing-error rights and restrictions on fees, rate changes, and mortgage practices. They do not impose a general interest-rate cap on all consumer loans or guarantee approval.
Does the Truth in Lending Act apply to installment loans?
TILA may apply to certain consumer installment loans, depending on the loan structure and legal requirements. Review the disclosures and the agreement before signing.
Does TILA limit how much interest a lender can charge?
No. TILA focuses on disclosure and transparency. It does not set a loan's cost or decide whether borrowing is right for you.
Why is APR important under TILA?
APR lets you compare the cost of credit across offers, because it expresses certain borrowing costs as a yearly percentage.
What should I review before signing a loan agreement?
Review the APR, finance charge, amount financed, total of payments, payment schedule, fees, and the consequences of missed payments.
Recent Articles
Emergency Car Repair Loans: Fast Help for Urgent Repairs
Emergency car repair loans explained. Learn costs, approval factors, risks, ...Installment Loans Corpus Christi: Funding Timelines
Installment loans Corpus Christi: how funding timing works, what affects it,...Hardship Loans for Bad Credit: Options, Rates, and Risks
Hardship loans for bad credit explained. Learn how they work, who qualifies,...Personal Loans Orlando: How to Streamline Your Application
Personal loans Orlando borrowers can prepare for by gathering the right docu...Loan Application Process: What Happens After You Submit
The loan application process doesn't end at submit. See the review timeline,...Short Term Personal Loans: Compare Options in 2026
Short term personal loans explained with lender options, costs, and tips to ...Get your money today
Apply for a loan NOW!
Applying does NOT affect your FICO® Score!
Have questions?
Please call us by phone:
Credit Cube © 2026. All rights reserved
CreditCube is a Tribal enterprise, wholly owned and operated by the Big Valley Band of Pomo Indians, a federally-recognized American Indian tribe and sovereign government. Any Agreement entered into as a result of this Application shall be governed by applicable Tribal and federal law. Each aspect of communication and transaction with/on this site will be deemed to have occurred in CreditCube’s Big Valley Band of Pomo Indian Reservation offices, regardless of the location where you are accessing or viewing this site.
⚠ Please note: This is an expensive form of borrowing. CreditCube loans are designed to assist you in meeting your short-term borrowing needs and are not intended to be a long-term financial solution! Examples of emergency reasons why these loans might be used include unexpected emergencies, car repair bills, medical care, or essential travel expenses.
* Loan approvals are subject to underwriting. Approval may take longer if additional verification documents are requested. Not all loan requests are approved. CreditCube reviews your information in real-time to determine whether your information meets our lending criteria. You acknowledge that by completing and submitting the website application that you are applying for a Loan. We verify applicant information through national databases including, but not limited to, Clarity Services, Inc., a credit reporting agency, and we may pull your credit in order to determine your eligibility and ability to repay.
** Maximum loan amount is $500 for first-time customers. For returning CreditCube customers, rates may go down over time based on your CreditCube Loyalty Program status and your payment history with us. Please see our Loyalty Program page for more information.
*** Loan Applications processed and approved before 3pm EST Monday-Friday are typically funded on the next business day. Example: If your loan is processed and approved on Friday before 3pm EST, the loan will typically be funded on the following Monday. Deposit times may vary depending on your bank. Business Day means Monday through Friday excluding all federal banking holidays.
CreditCube does not lend to residents of Pennsylvania, Connecticut, Minnesota, New York, Vermont, Virginia, West Virginia, Illinois, Georgia and North Carolina. Availability of installment loans in your state is subject to change at any time with or without notice at the sole discretion of CreditCube.