Exploring Green Loans for Bad Credit Borrowers
If a debt collector contacts you, FDCPA guidelines spell out what they may and may not do. The Fair Debt Collection Practices Act is a federal law that limits abusive, unfair, and deceptive debt collection. It protects you without erasing any debt you actually owe.
This guide explains the main rules in plain English. You will learn the communication limits, what a validation notice should include, how disputes work, and the steps to take when a notice arrives. Along the way, it points you to the federal regulators that enforce these rules.
This article is general information only, not legal advice. For help with your specific situation, consider speaking with a qualified attorney or a nonprofit credit counselor.
What Are Green Loans for Bad Credit?
Green loans for bad credit are financing options, often used for energy-efficient or environmentally focused expenses, that some lenders may offer to borrowers with limited or damaged credit. Bad credit means your credit history may be limited, damaged, or poor. It can affect your eligibility, but it does not always rule you out.
Some lenders look at more than your credit score. They may weigh your income and your ability to repay as well. Even so, approval is never guaranteed. Common uses include a few energy-related projects:
- Energy-efficient HVAC. A more efficient heating or cooling system.
- Solar-related costs. Panels or related equipment.
- Insulation. Upgrades that cut energy waste.
- Energy-saving appliances. Lower-consumption models.
- Windows or weatherization. Sealing and efficiency improvements.
- Emergency home energy repairs. Urgent fixes that restore efficiency. The specific project shapes whether a green loan fits. Next, here is a closer look at eligible uses.
What Can Green Loans Be Used For?
Green loans may be used for expenses that improve energy efficiency or serve an environmental purpose. The exact list depends on the lender and your loan agreement.
- Energy-efficient appliances. Lower-consumption models for the home.
- Home insulation. Upgrades that reduce energy loss.
- Solar-related improvements. Panels and related equipment.
- HVAC repairs or replacement. More efficient heating and cooling.
- Water-saving systems. Fixtures and systems that cut water use.
- Weatherization. Sealing and efficiency work around the home.
- Emergency repairs that improve energy efficiency. Urgent fixes with an efficiency benefit.
Eligible uses vary by lender and loan agreement. Before applying, confirm whether your intended expense qualifies. That check matters even more when your credit is poor.
Can You Get Green Loans With Bad Credit?
You may be able to get a green loan with bad credit, though approval is harder and never guaranteed. Bad credit can make the review tougher, but some lenders work with borrowers who have less-than-perfect credit.
These lenders may look at several factors beyond your score. They can review your income, banking activity, debt obligations, payment history, and repayment ability. The trade-off is cost: terms may be more expensive for bad-credit borrowers, so the full agreement deserves a close read.
One caution matters most here. Avoid any lender that promises guaranteed approval, since that is a warning sign. Be cautious, too, with a lender that promises approval regardless of credit or asks for upfront fees before providing loan funds. The Texas Attorney General warns that “no credit check required” and “bad credit OK” offers can be suspicious, and it cautions against upfront-fee loan scams; you can read its guidance on the Texas Attorney General site.
How the TX Loan Process Works
The TX loan process may include checking state availability, reviewing eligibility, submitting an application, reviewing the terms, and signing only if repayment fits your budget. Rules can differ by city, so borrowers comparing local options like installment loans in Corpus Christi should still confirm the details for their own situation. Here is each step in turn.
Step 1. Check state availability
Loan availability may depend on the lender, the product, your location, and state rules. Our guide to installment loans in Texas covers how these loans work across the state. Confirm the loan is offered where you live before you go further.
Step 2. Review eligibility requirements
Lenders weigh several general factors before a decision. Common ones include:
- Age. You must meet the minimum age to borrow.
- Identity. A valid ID confirms who you are.
- Income. Proof that you can support repayment.
- Bank account. An active account for funding and payments.
- Repayment ability. A review of whether the payment fits your budget.
- State availability. Confirmation that the loan is offered in your state.
Step 3. Submit an online application
You enter your personal, income, and banking details in the online form. Accuracy helps, since gaps can slow the review. Approval, loan amount, and timing are never promised.
Step 4. Review loan terms
Before you agree, review the details that decide the real cost:
- Total repayment amount. The full amount you will repay.
- APR. The yearly cost of the credit.
- Fees. Any charges beyond interest.
- Payment schedule. When and how much each payment is.
- Late-payment consequences. What happens if a payment is missed.
- Early repayment rules. Whether you can pay off early.
- State-specific disclosures. Any terms required in your state.
Step 5. Sign only if repayment fits your budget
Sign the agreement only once the terms are clear and the payment fits your budget. Borrow only what you need, and keep a repayment plan in mind before you commit.
This section describes a general process, not financial advice. The steps and timing can differ by lender, and nothing here guarantees approval or a funding date.
CreditCube and Green Loans for Bad Credit Borrowers
CreditCube offers tribal installment loans for eligible borrowers. If you are researching green loans for bad credit, CreditCube may be one of the options to review when you need an installment-style repayment structure. You need to keep in mind that this is an expensive form of borrowing, with APRs ranging from 200% to 700%.
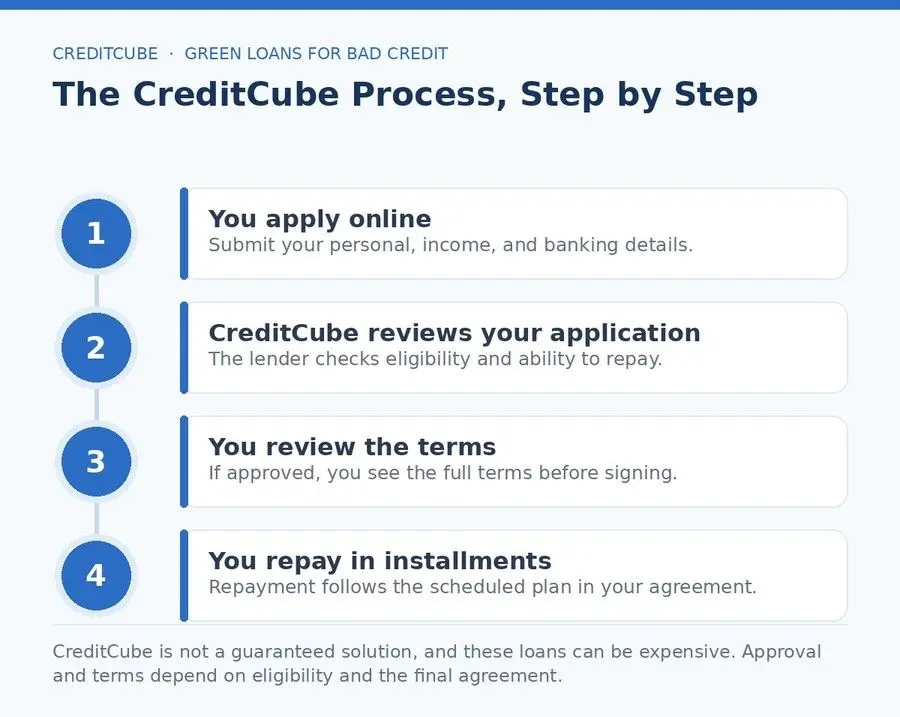
The process runs online and follows a few steps:
- You apply online. You submit your personal, income, and banking details through the form.
- CreditCube reviews your application. The lender checks your eligibility and your ability to repay.
- You review the terms. If you are approved, you see the full terms before signing.
- You repay in installments. Repayment follows the scheduled plan in your agreement. CreditCube is not a guaranteed solution, and these loans can be expensive, so review the full agreement first. It is a tribal installment lender, not a certified green loan provider. To see how an installment loan compares with other products, look at them side by side.
What to Check Before Applying for Green Loans With Bad Credit
Before you apply, confirm the loan is for a green purpose, the lender explains eligible uses, and you understand the APR, fees, and total repayment. Run through each question below.
- Green purpose. Is the loan actually for a green or energy-related purpose?
- Eligible uses. Does the lender explain what the funds can cover?
- APR. What is the APR?
- Fees. What are the fees?
- Total repayment. What is the total repayment amount?
- Payment dates. What are the payment dates?
- Missed payments. What happens if a payment is missed?
- State availability. Is the lender clear about state availability?
- Budget fit. Does repayment fit your budget?
- Alternatives. Are there lower-cost alternatives? If the answers hold up, a green loan may be worth considering. Here is when that tends to be the case.
When Do Green Loans Make Sense?
A green loan may make sense when the expense is necessary, the project reduces energy use or restores an essential home function, and repayment fits your budget. In short, it fits best when the need is real and the math works.
A few more conditions should hold first. You should understand the full repayment cost and have reviewed your alternatives. And you should not need another loan to repay this one. When these line up, borrowing may be a reasonable step. Even so, some situations point the other way.
When Should You Consider Something Else?
A green loan may not be the right choice when the expense is not urgent, the project can wait, or repayment would strain your essentials. In those cases, borrowing tends to deepen the problem.
Watch for these warning signs:
- Non-urgent expense. The cost is not urgent, or the project can be delayed.
- Essentials at risk. Repayment would affect rent, utilities, food, insurance, or other essentials.
- Existing debts. You already carry several debts.
- Unclear repayment. You are unsure how you will repay.
- Unclear terms. The lender does not clearly disclose the terms.
- Guaranteed-approval promises. The lender promises guaranteed approval. If any of these fit, the alternatives below are the safer first step.
Alternatives to Green Loans for Bad Credit
A loan is not the only way to fund an energy project. Before you borrow, these lower-cost options are worth a look.
- Utility company energy-efficiency programs. Many utilities offer rebates or upgrade help.
- Local weatherization assistance. Community programs may cover efficiency work.
- Manufacturer financing. Some makers offer financing on appliances or systems.
- Contractor payment plans. A contractor may let you pay over time.
- Credit union small-dollar loans. Members may find lower-cost small loans.
- Savings. Using savings avoids new debt.
- Budget adjustments. Trimming other spending may free up funds.
- Employer paycheck advance. Some employers advance part of your next check.
- Nonprofit financial counseling. A counselor can help you build a plan for little or no cost. Confirm availability and eligibility for any program in your state before you rely on it. If a loan still fits after that, one final checklist helps.
Responsible Borrowing Checklist
Before applying, confirm you know why you need the loan, you understand the total cost, and you can repay without missing essential bills. Answer yes to each of these.
- I know why I need the loan.
- I know the total repayment amount.
- I understand the APR and fees.
- I know the payment schedule.
- I have compared alternatives.
- I can repay without missing essential bills.
- I understand what happens if I miss a payment.
- I have read the full agreement.
Still have questions? These come up often.
FAQs About Green Loans for Bad Credit
What are green loans for bad credit?
Green loans for bad credit are financing options that borrowers with poor or limited credit may consider for energy-efficient or environmentally focused expenses. Approval, costs, terms, and availability depend on the lender, your financial profile, state rules, and the final loan agreement.
Can I get green loans with bad credit?
Bad credit may make approval harder, but some lenders review more than your credit score. They may also consider income, repayment ability, banking history, and existing debt. Approval is not guaranteed.
Are green loans the same as personal loans?
Not always. Some green loans are personal loans used for energy-efficient or environmentally focused expenses. Other green loans may have specific use-of-proceeds requirements.
What is the TX loan process?
The TX loan process may include checking state availability, reviewing eligibility, submitting an application, reviewing terms, and signing an agreement if repayment fits your budget. Loan availability and terms can vary by state, so check that a lender offers loans in Texas before you apply.
Can I use a green loan for home repairs?
Some green loans may be used for home repairs if the repairs improve energy efficiency or meet the lender’s eligible-use rules. Confirm eligible uses before applying.
Are green loans for bad credit guaranteed?
No. Be cautious of any wording that suggests guaranteed approval. Lenders may review credit history, income, repayment ability, state availability, and other eligibility factors.
What should I check before applying?
Check the APR, fees, total repayment amount, payment schedule, state availability, eligible uses, missed-payment consequences, and whether repayment fits your budget.
Recent Articles
Bank Statement Loan Review: What Lenders Check
A bank statement loan review helps lenders assess income and underwriting fa...Installment Loans for Bad Credit in 2026: Rates, Terms & Options
Installment loans for bad credit explained. Learn terms, costs, approval rul...Loans Like My Quick Wallet: Best Alternatives in 2026
Explore fast loan apps like My Quick Wallet, with CreditCube offering the be...Managing Debt: Risks of Taking Multiple Loans at Once
Managing debt gets harder with every new loan. Learn loan stacking risks, wa...Personal Loan Hialeah FL: Funding Timelines Explained
Getting a personal loan in Hialeah, FL? Learn what affects funding timelines...Loan Application Process: What Happens After You Submit
The loan application process doesn't end at submit. See the review timeline,...Get your money today
Apply for a loan NOW!
Applying does NOT affect your FICO® Score!
Have questions?
Please call us by phone:
Credit Cube © 2026. All rights reserved
CreditCube is a Tribal enterprise, wholly owned and operated by the Big Valley Band of Pomo Indians, a federally-recognized American Indian tribe and sovereign government. Any Agreement entered into as a result of this Application shall be governed by applicable Tribal and federal law. Each aspect of communication and transaction with/on this site will be deemed to have occurred in CreditCube’s Big Valley Band of Pomo Indian Reservation offices, regardless of the location where you are accessing or viewing this site.
⚠ Please note: This is an expensive form of borrowing. CreditCube loans are designed to assist you in meeting your short-term borrowing needs and are not intended to be a long-term financial solution! Examples of emergency reasons why these loans might be used include unexpected emergencies, car repair bills, medical care, or essential travel expenses.
* Loan approvals are subject to underwriting. Approval may take longer if additional verification documents are requested. Not all loan requests are approved. CreditCube reviews your information in real-time to determine whether your information meets our lending criteria. You acknowledge that by completing and submitting the website application that you are applying for a Loan. We verify applicant information through national databases including, but not limited to, Clarity Services, Inc., a credit reporting agency, and we may pull your credit in order to determine your eligibility and ability to repay.
** Maximum loan amount is $500 for first-time customers. For returning CreditCube customers, rates may go down over time based on your CreditCube Loyalty Program status and your payment history with us. Please see our Loyalty Program page for more information.
*** Loan Applications processed and approved before 3pm EST Monday-Friday are typically funded on the next business day. Example: If your loan is processed and approved on Friday before 3pm EST, the loan will typically be funded on the following Monday. Deposit times may vary depending on your bank. Business Day means Monday through Friday excluding all federal banking holidays.
CreditCube does not lend to residents of Pennsylvania, Connecticut, Minnesota, New York, Vermont, Virginia, West Virginia, Illinois, Georgia and North Carolina. Availability of installment loans in your state is subject to change at any time with or without notice at the sole discretion of CreditCube.