What Are Indian Reservation Loans for Bad Credit?
Indian reservation loans for bad credit are usually tribal installment loans from lenders tied to a Native American tribe. A low credit score won’t automatically shut you out. The lender still checks your income and whether you can keep up with the payments. These loans are repaid in scheduled installments with interest and fees, and they are typically much more expensive than a bank or credit union loan.
CreditCube is a tribal lender that offers tribal loans structured as installment loans for eligible borrowers, not lump-sum payday loans. This guide explains how these loans work, how CreditCube reviews applications, what to check before you sign, and how to compare lower-cost alternatives.
How Does CreditCube Review Applications for Bad Credit?
CreditCube reviews applications by looking at more than a credit score. The review may consider your identity, income, bank account information, state availability, and ability to repay. Bad credit does not automatically mean approval or denial, and approval is never guaranteed.
When you apply, CreditCube may review:
- Identity information
- Income source
- Bank account and banking activity
- State availability for your location
- Credit and repayment-related factors
- Ability to repay the loan
- Accuracy of your application details
Accurate details help the review move smoothly, but they do not change the fact that approval depends on the lender’s decision.
How to Apply for Indian Reservation Loans for Bad Credit Online
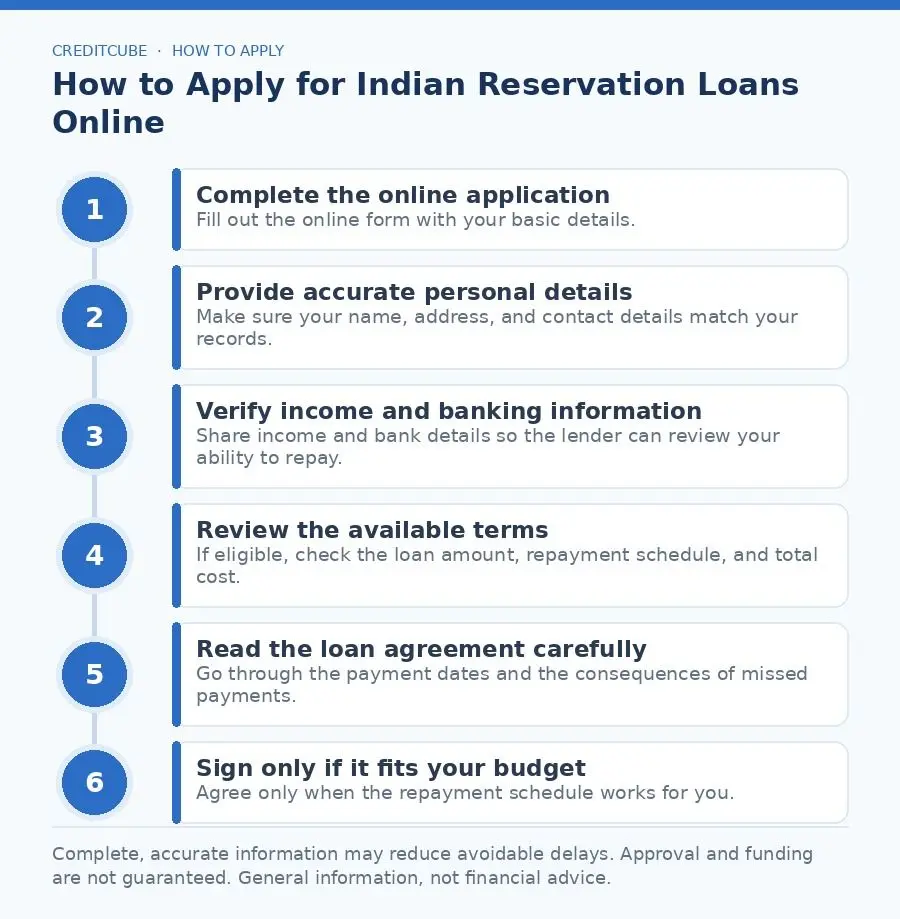
Applying online for these loans follows a few clear steps, from completing the form to signing only if the terms fit. The steps below show the general order. Before you apply, it helps to review the bad credit loan requirements so your information is complete and accurate.
-
Complete the online application Start by filling out the online form with your basic details. A complete form helps the lender begin the review without delay.
-
Provide accurate personal details Make sure your name, address, and contact details match your records. Accurate details reduce the chance of a verification problem later.
-
Verify your income and banking information The lender may ask for income and bank account details to confirm your ability to repay. Having these ready can keep the process moving.
-
Review the available terms if you are eligible If you qualify, look closely at the loan amount, repayment schedule, and total cost. This is the point to compare the offer against your budget.
-
Read the loan agreement carefully Go through the full agreement, including the payment dates and the consequences of missed payments. Do not move forward until every term is clear.
-
Sign only if the repayment schedule fits your budget Signing creates a repayment obligation, so agree only when the payments work for you. If the schedule feels tight, it is safer to wait.
Submitting complete and accurate information may help reduce avoidable delays. It does not guarantee approval or funding, so you should still review every term before you agree.
How Can California Applicants Prepare Before Applying?
California applicants can prepare by making sure their application details are accurate before they submit. For CA application efficiency, check that your legal name, current California address, income details, bank information, and identification are all correct. Complete information can reduce avoidable review issues, but eligibility, availability, approval, and terms still depend on lender review and the final agreement.
Use this checklist before you apply from California:
- Confirm your legal name
- Use your current California address
- Prepare your income details
- Confirm active checking account information
- Review state availability
- Read the final loan agreement before signing
Preparing these details supports CA application efficiency, but it is not a promise of approval or specific loan terms.
Why Do Bad Credit Borrowers Search for Indian Reservation Loans?
Borrowers search for these loans because traditional lenders may rely heavily on credit scores. Some borrowers have limited credit history, and some simply want an online application process. Tribal installment lenders may review more than a credit score, though your ability to repay still matters.
Poor credit does not automatically mean approval or denial. Lenders may review income, repayment ability, banking information, and other eligibility factors before making a decision. A borrower should still compare the full cost against other options before applying.
Indian Reservation Loans vs. Payday Loans: What’s the Difference?
The main difference is the repayment structure. Indian reservation loans are often tribal installment loans repaid in scheduled payments, while payday loans are often repaid in one lump sum. Both can be expensive, so review the full terms before you borrow. The table compares the two.
| Feature | Indian reservation loans / tribal installment loans | Payday loans |
|---|---|---|
| Repayment | Usually scheduled installments | Often one lump-sum payment |
| Credit profile | May consider bad credit borrowers | May vary by lender |
| Cost | Can be expensive; review full terms | Can also be expensive |
| Timeline | Depends on lender review and agreement | Often short-term |
| Key risk | Missed payments and high borrowing cost | Rollover and lump-sum repayment pressure |
Scheduled installments do not make a loan cheap or risk-free. Review the full agreement and compare the total cost before signing.
If you only need a small amount, compare the total cost of any small-dollar option, including $255 payday loans, before you borrow, since smaller loans can still carry high fees.
What Should You Check Before Accepting a Loan Agreement?
Before accepting any loan agreement, review the full cost and the repayment plan, not just the amount you receive. Start with the total repayment amount, the APR, and the fees, since these show what the loan really costs. Then check the payment dates, the number of payments, and what happens if a payment is late, so the schedule holds no surprises.
Tribal lenders operate under tribal law and applicable federal law, so the protections and terms may differ from those of state-licensed lenders. Check the lender’s licensing or regulatory information, such as a state license or a tribal regulatory authority, before you apply. Finally, make sure the agreement matches what you expected, and do not sign until every term is clear to you.
When Might Indian Reservation Loans for Bad Credit Make Sense?
A tribal installment loan may be worth considering when the expense is necessary and temporary and you understand the total repayment amount. A loan can fit when you have stable income, the payments fit your budget, and you have compared other options first. It is a closer match when you do not need another loan to repay this one. Even in these cases, borrowing should be a careful decision rather than an automatic one.
When Borrowing Could Make Things Harder
Borrowing may not be appropriate when you are already unable to cover essential bills or you are unsure how you will repay. It is a poor match if you already have several active debts or you would need another loan to repay this one.
A loan also does not fit when the money would cover non-essential spending, when you have not reviewed the full cost, or when repayment would create a larger financial problem. If the payments would interfere with rent, utilities, food, or insurance, it is safer to wait and look at other options.
Alternatives to Indian Reservation Loans for Bad Credit
Several alternatives may cost less or fit your budget better. It helps to compare these options before you borrow:
- A payment plan with a service provider. Many utility, medical, and phone providers will spread a bill over time. Ask before the due date, since an early plan often avoids late fees.
- An employer paycheck advance. Some employers let you draw part of your earned pay before payday. This can cover a short gap, though some programs charge fees, so check the terms first.
- Emergency savings, if you have them. Using your own savings avoids new debt entirely. Plan to rebuild the fund after you spend from it.
- A credit union small-dollar loan. Credit unions often offer small loans with lower rates than short-term products. You may need to join first, so check the terms.
- A budget adjustment. Pausing non-essential spending for a short period can cover a small shortfall. Review recent expenses to see what you can delay.
- Nonprofit credit counseling. A nonprofit counselor can help you build a repayment plan at low or no cost. Look for an accredited agency so the advice is reliable.
- Asking creditors about hardship options. Some creditors offer hardship plans for a specific bill, and some providers offer financing, such as bad credit dental financing. Ask what support is available, and compare the cost of any financing, before you borrow.
Alternatives may not be available in every situation, but comparing options can help borrowers avoid unnecessary debt.
Questions to Ask Yourself Before You Apply
A few honest questions can help you decide whether to borrow at all. Ask yourself the following before you apply:
- Do I need this loan for a necessary expense?
- Do I know the total cost?
- Can I make every scheduled payment?
- Have I checked alternatives?
- Do I understand what happens if I miss a payment?
- Is the loan available in my state?
- Have I read the full agreement?
If you cannot answer these clearly, it is worth pausing before you apply.
How CreditCube Supports Borrowers Through the Process
CreditCube supports borrowers with an online application and clear review steps, so you can see the terms before you decide. Repayment is made through scheduled installments set by the final agreement, and you can review that agreement before signing. CreditCube is a tribal installment loan provider, not a traditional payday lender, and approval and funding are never guaranteed.
Before you apply, review the available terms, compare alternatives, and confirm that the repayment schedule fits your budget. When you are ready, you can review CreditCube installment loan options and start your application only after reviewing the terms.
FAQ About Indian Reservation Loans for Bad Credit
What does “Indian reservation loans for bad credit” mean?
Indian reservation loans for bad credit usually refer to tribal installment loans that may be considered for borrowers with imperfect credit. Approval, terms, costs, and availability depend on lender review, state availability, and the final loan agreement.
Can I get an Indian reservation loan with bad credit?
Bad credit may not automatically prevent you from qualifying, but approval is not guaranteed. Lenders may review income, banking information, identity details, repayment ability, and other eligibility factors.
Are Indian reservation loans the same as payday loans?
Not always. Many tribal loans are structured as installment loans, which means repayment happens through scheduled payments. Payday loans are often repaid in one lump sum instead.
Do Indian reservation loans require a credit check?
Lenders may review credit-related information, income, bank activity, and repayment ability. The exact review process depends on the lender and the application.
How fast can I get a decision?
Decision timing depends on the lender’s review process, the accuracy of your application, verification steps, and state availability. You should not assume an instant or guaranteed decision.
What does CA application efficiency mean?
CA application efficiency means preparing accurate, complete information before applying as a California applicant. This may help reduce avoidable review delays, but it does not guarantee approval, funding, or specific loan terms.
What should I check before accepting a tribal installment loan?
Review the APR, fees, total repayment amount, payment schedule, and state availability. Also confirm the missed-payment consequences and whether the payments fit your budget before you sign.
Recent Articles
High Interest Loan Laws: Understanding Tribal Installment Loans
Learn how high interest loan laws vary by state and how tribal installment l...Weekend Payday Loans: What to Know Before You Apply
Weekend payday loans explained. Learn about eligibility, funding timelines, ...Smart Financial Planning Tips Every Student Needs in 2026
Smart financial planning for students in 2026: budget tips, savings strategi...Loans in Irving TX: What Affects Your Funding Time
Loans in Irving TX explained: see what shapes your funding timeline and what...What to Look for in a Loan Provider
Taking out a loan is a serious decision that should be preceded by a suffici...How ‘Buy Now, Pay Later’ Could Destroy Your Credit Score!
Discovering how to buy now pay later credit services in 2025 can silently da...Get your money today
Apply for a loan NOW!
Applying does NOT affect your FICO® Score!
Have questions?
Please call us by phone:
Credit Cube © 2026. All rights reserved
CreditCube is a Tribal enterprise, wholly owned and operated by the Big Valley Band of Pomo Indians, a federally-recognized American Indian tribe and sovereign government. Any Agreement entered into as a result of this Application shall be governed by applicable Tribal and federal law. Each aspect of communication and transaction with/on this site will be deemed to have occurred in CreditCube’s Big Valley Band of Pomo Indian Reservation offices, regardless of the location where you are accessing or viewing this site.
⚠ Please note: This is an expensive form of borrowing. CreditCube loans are designed to assist you in meeting your short-term borrowing needs and are not intended to be a long-term financial solution! Examples of emergency reasons why these loans might be used include unexpected emergencies, car repair bills, medical care, or essential travel expenses.
* Loan approvals are subject to underwriting. Approval may take longer if additional verification documents are requested. Not all loan requests are approved. CreditCube reviews your information in real-time to determine whether your information meets our lending criteria. You acknowledge that by completing and submitting the website application that you are applying for a Loan. We verify applicant information through national databases including, but not limited to, Clarity Services, Inc., a credit reporting agency, and we may pull your credit in order to determine your eligibility and ability to repay.
** Maximum loan amount is $500 for first-time customers. For returning CreditCube customers, rates may go down over time based on your CreditCube Loyalty Program status and your payment history with us. Please see our Loyalty Program page for more information.
*** Loan Applications processed and approved before 3pm EST Monday-Friday are typically funded on the next business day. Example: If your loan is processed and approved on Friday before 3pm EST, the loan will typically be funded on the following Monday. Deposit times may vary depending on your bank. Business Day means Monday through Friday excluding all federal banking holidays.
CreditCube does not lend to residents of Pennsylvania, Connecticut, Minnesota, New York, Vermont, Virginia, West Virginia, Illinois, Georgia and North Carolina. Availability of installment loans in your state is subject to change at any time with or without notice at the sole discretion of CreditCube.